HUD 232 Mortgage Compliance Calendar for Skilled Nursing Facilities From Fiscal Year Close to REAC Submission
A compliance calendar coordinates HUD 232 borrower audits, operator reports, and inspections.
HUD 232 audit and compliance for skilled nursing facilities requires separate borrower annual filings, operator quarterly reports, and a conditional assessment of physical inspection obligations. For-profit borrowers must deliver audited annual financial statements within 90 days of fiscal year end, while non-profit borrowers follow a different audit timetable. The practical core is a coordinated calendar that begins before year-end.
Why HUD 232 borrowers face a more demanding compliance calendar than conventional healthcare borrowers
Federal mortgage insurance comes with more requirements than conventional healthcare real estate debt. HUD’s Office of Residential Care Facilities (ORCF) checks for cash deficiencies, distributions made without surplus cash, and going-concern risk after closing. Oversight does not end when the loan closes. A licensed care facility with HUD-insured debt must follow the Section 232 Handbook and the Uniform Financial Reporting Standards at 24 CFR 5.801 and 24 CFR 200.36.
HUD reported that its active Section 232 mortgage insurance portfolio covered more than 3,800 residential care facilities as of June 2026. Within that portfolio, reporting is both an annual lender requirement and part of continuing asset oversight. A late or deficient filing can raise compliance flags, while failures under the loan’s requirements can create technical-default risk. The calendar therefore has several overlapping tracks. Borrowers and operators must plan ahead for borrower annual reporting, operator quarterly reporting, and any physical inspection obligations that apply, because each has its own requirements.
What are the annual audit requirements, and how do borrower and operator obligations differ?
For-profit borrowers must electronically submit an audited Annual Financial Statement (AFS) within 90 days of fiscal year end.
Non-profit borrowers must submit a borrower-certified, unaudited AFS by the initial reporting deadline, with an audited AFS due no later than nine months after fiscal year end pursuant to 2 CFR 200.
That distinction changes the sequence of audit work. Borrower financial statements must use the accrual basis of accounting and include a certification signed by the owner and, if applicable, the management agent. The certification confirms that the statements are complete and accurate. Thus, the calendar must allow for owner review as well as the auditor’s work.
Operators have a separate reporting track under HUD guidance effective for fiscal years commencing on or after December 2, 2014. They submit operator-certified quarterly and year-to-date financial statements to both the lender and HUD. Quarterly and year-to-date reports are due within 60 days of the end of the period, though final fiscal year-to-date reporting has a longer year-end deadline. Operator financials are used to calculate debt service coverage and must reconcile to the trial balance, cost reports, and master lease or rent obligations between the operator and the borrower.
What happens when the standard reporting cadence is insufficient? ORCF can require more frequent or audited statements from either entity after a covenant breach, declining occupancy, or submissions that appear unreliable.
The 90-day window in practice — what has to happen between fiscal year close and the submission deadline
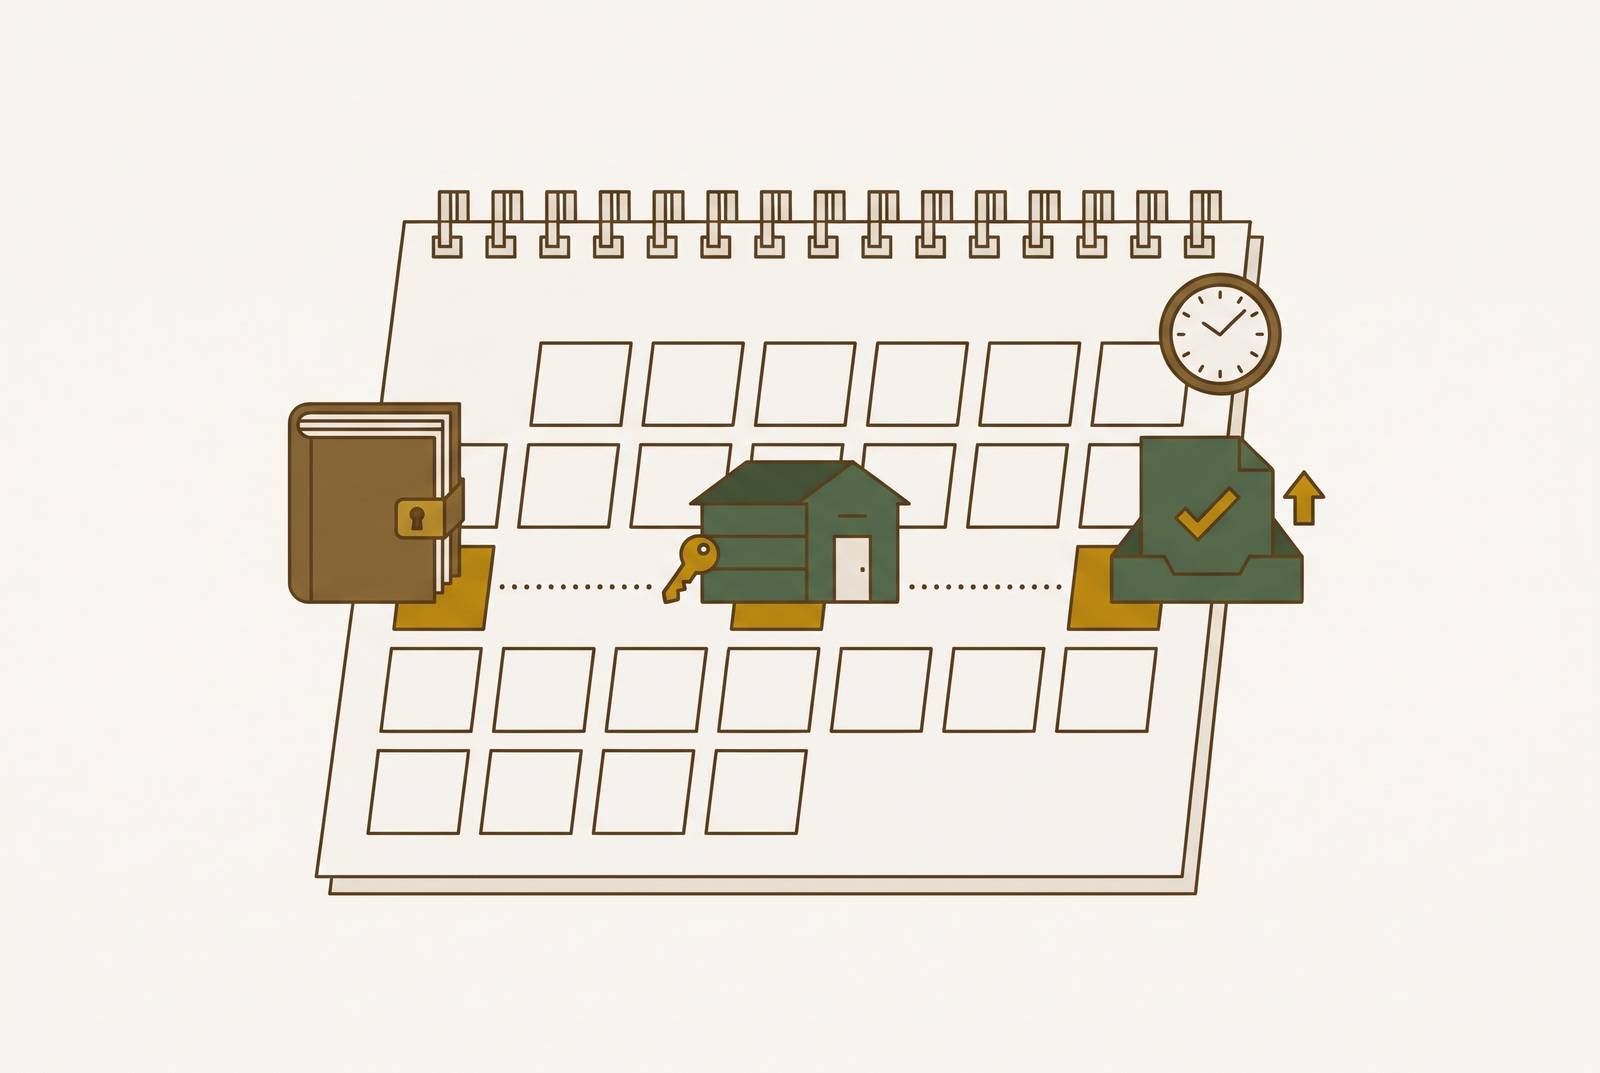
For a borrower whose fiscal year ends on December 31, the calendar in this example works back from delivery of audited financial statements on March 31. Records must be substantially complete and available to the auditor by mid-January at the latest. That leaves time for fieldwork, draft review, management response, and final issuance. The deadline marks delivery of the completed audit. Treating the entire window as time to gather records leaves the substantive audit work competing with submission preparation.
The required package also extends beyond the financial statements. HUD’s audit package requirements include an Auditor’s Report on Financial Statements, an Independent Auditor’s Report on Internal Control Over Financial Reporting and on Compliance and Other Matters, and an Auditor’s Report on Compliance. Each belongs in the preparation schedule, rather than being treated as an attachment to consider after the statements are finished. Borrowers must also provide an Auditor’s Management Letter or Schedule of Findings and Questioned Costs, and Auditor’s Comments on Audit Resolution Matters. Those items may be submitted independently.
The sequence is the same for other fiscal years. The actual year-end anchors the 90-day count, while the work proceeds backward from delivery through final issuance, management response, draft review, fieldwork, and record readiness. Operator quarterly deadlines may fall inside that same preparation window.
Electronic submission through FASS and what REAC actually does with the financial data
The Section 232 Handbook requires borrowers to submit annual financial statements electronically through the Financial Assessment Subsystem (FASS). FASS uploads the statements into the Integrated Real Estate Management System (iREMS), which ORCF uses for routine asset management. Submission is not merely the last administrative step. It places the borrower’s financial information into the system used for continuing oversight, where gaps, errors, and late filings become visible to account executives.
The Real Estate Assessment Center (REAC) collects and assesses financial statements on multifamily projects and provides ORCF project managers with information about compliance deficiencies and performance risks. In Section 232 compliance, it does more work on financial assessment than on physical inspection. An operator who associates REAC only with inspectors may overlook the financial review that follows the annual submission, even when the facility is exempt from routine physical inspections.
The handbook describes ORCF account executives’ quarterly and annual reviews of financial performance using iREMS data. Those reviews can flag properties with debt service coverage below HUD’s target and lead to enforcement when warranted. Mortgagees and servicers also have routine portfolio review and risk-reporting duties.
Whether skilled nursing facilities face routine REAC physical inspections, and what determines that answer
Most skilled nursing facilities do not face routine REAC physical inspections, but the answer depends on when the facility entered the insured portfolio and its inspection history. An October 2012 regulatory change exempted SNFs because they already undergo approximately annual CMS inspections. Facilities insured after October 2012 are not subject to routine REAC physical inspections. Earlier entry requires a more conditional answer. For an SNF that remains subject to inspection, the physical inspection calendar must still be addressed separately from financial reporting.
For non-SNF facilities in the Section 232 portfolio that remain subject to REAC, scores determine reinspection frequency and potential enforcement. A score of 90 or higher places a property in Standard 1, with inspection once every three years. A score below 80 places it in Standard 3, with annual reinspection. A score below 60 is a failing grade, and two scores below 60 in a row may lead to referral to HUD’s Departmental Enforcement Center. A score of 30 or below must be referred automatically.
For an SNF still subject to REAC, clinical safety can complicate inspection preparation. Facilities may limit access to windows for residents with Alzheimer’s or dementia, but REAC treats window restrictions as deficiencies. ORCF can resolve that conflict by making database adjustments before inspection for facilities that qualify. Timing is essential to that accommodation. Separately, Notice PIH 2025-27, published September 30, 2025, extends the start of scoring new affirmative requirements under NSPIRE, the successor physical inspection standard, to October 1, 2026, for inspections in the Public Housing and Multifamily Housing portfolios.
What the April 2026 OIG findings reveal about what happens when the calendar slips
HUD’s oversight office (OIG) reported in April 2026 how failures in reporting and oversight went hand in hand with financial distress and the risk of enforcement. Audited statements disclosed borrower withdrawals when properties lacked available surplus cash, cash deficiencies, and insufficient cash flow to pay current debts. These were not merely incomplete filing records. The statements contained evidence of conditions affecting the properties’ ability to meet their obligations, with consequences for borrowers, lenders, and residents.
The OIG recommended referral to the Departmental Enforcement Center for a civil money penalty or other enforcement action within 60 days of receipt of financial statements when unauthorized distributions had not been repaid in a timely manner. The sequence links repayment and referral to financial review. It does not support treating an unresolved distribution as something that can wait until the next annual audit. Nor does the stated recommendation supply a separate fixed repayment period that can safely be substituted for “a timely manner.”
The same report found that reduced staffing compounded the borrower failures. Between October 2024 and May 2025, the average number of properties managed by each ORCF staff member rose from roughly 60–80 to roughly 165–200. ORCF did not receive required audited statements from all borrowers, secure all required action plans, or notify the enforcement center before borrowers defaulted. Complete, accurate submissions with records to back them up help reduce friction and settle questions faster, while leaving missing work for the agency to find depends on its follow-up.
Tax and ownership implications of the annual compliance cycle for closely held Section 232 borrowers
For closely held borrowers, which make up most of the Section 232 portfolio, the audit establishes facts that drive tax reporting. Surplus cash determinations, reserve restrictions, and findings of unauthorized distributions affect what goes on the owner’s individual or pass-through return. The audit and tax calendars therefore intersect. For an owner of a single-asset, special-purpose borrower entity, the question is not simply when a return is due, but whether the financial facts underlying that return have been resolved.
The owner’s certification makes that connection concrete. The owner and, if applicable, the management agent must state that they reviewed the financial statements and consider them complete and accurate. An inaccurate certification creates legal exposure, so signing is not a substitute for understanding the treatment of cash and distributions. Restricted reserve balances illustrate the problem. Treating those balances as operating cash that can be used before a surplus cash determination causes problems with both HUD compliance and tax characterization.
Tax advisory work should be coordinated with the audit timeline rather than begun after the financial decisions have been made. That coordination allows owners to structure distributions, reserve contributions, and related-party transactions in ways defensible to HUD and tax authorities. It also keeps the advisory discussion grounded in the borrower’s actual restrictions. The relevant planning starts with what the audited records establish about cash available to the owner.
Building the compliance calendar into an annual operating rhythm rather than a deadline sprint
Borrowers should set the date for getting records to the auditor before fiscal year end. That gives fieldwork a defined starting point and preserves the 90-day window for review and response, with data gathering completed beforehand. Operator quarterly filings belong on the same calendar as borrower annual filings, while retaining their separate deadlines. Rolling reconciliation is the other essential discipline. Reconciling operator financials to the trial balance, cost reports, and master lease obligations throughout the year makes the year-end exercise a check of previously reconciled records.
Borrowers should confirm the applicable handbook version with the auditor at the start of each cycle, because provisions effective January 5, 2026 apply to all new transactional requests. For SNFs insured before October 2012 that remain subject to physical inspection, preparation should coordinate CMS survey schedules and REAC inspection windows. Any warranted database adjustments, including window-restriction accommodations, belong before inspection. These tasks require calendar space even though they do not all culminate in the annual financial submission.
Good records can support more than penalty avoidance. HUD launched its Express Lane program for Section 232 refinancing in July 2025, which rewards operators whose financial records and operational track records are already clean. Keeping up with the compliance calendar helps facilities be better prepared for expedited processing when they need to refinance.
Specialized audit support provides a practical way to manage these interdependent obligations. The relevant qualifications are knowledge of ORCF reporting standards, the operator-borrower structure, and the intersection of HUD compliance with tax planning. Those capabilities distinguish sustained Section 232 work from occasional familiarity with a HUD audit. They are not reserved for large portfolios. The calendar rewards systems over heroics, and audit and advisory support is most useful when it forms part of that system before the year closes.