Related-Party Transaction Disclosure Requirements for SNF Operators
CMS requires nursing homes to disclose all ownership and related-party relationships.
CMS said in the preamble to the final rule: "part of the challenge CMS faces in ensuring quality care at nursing homes is our lack of sufficient knowledge of all the parties associated with the nursing home's ownership, operations, and management". That is a regulator admitting it could not, until recently, reliably answer a basic question: who actually controls this building, and where does the money go once it enters the facility's accounts?
Why does ownership opacity matter so much in this particular setting? Because SNFs sit at the intersection of vulnerable residents and heavily leveraged capital structures, and when management fees, real estate leases, and staffing contracts all flow to affiliated companies, it becomes hard to tell whether resident care dollars are being diverted into related-party profit centers. CMS acknowledged, in adopting the rule, that the disclosure burden on facilities would be real and probably substantial. The agency concluded that tracing ownership and management relationships mattered enough, for quality of care and for protecting taxpayer-funded Medicare dollars, that the administrative cost was worth imposing anyway.
The rulemaking timeline and the pattern of repeated deadline extensions
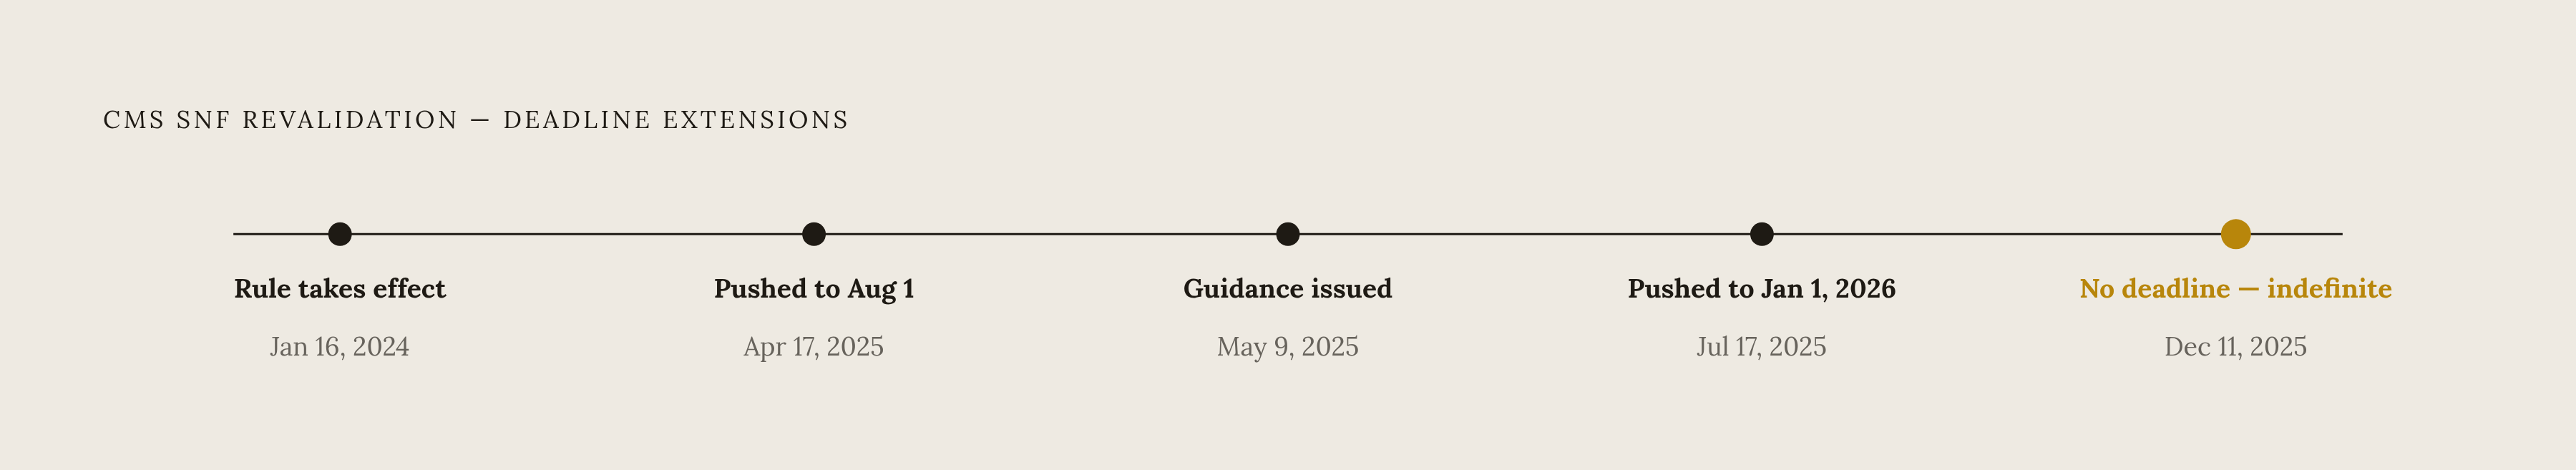
The rule took effect January 16, 2024, triggering off-cycle revalidations for every enrolled SNF in the country, with no exceptions for size or structure https://hallrender.com/2025/07/17/cms-extends-yet-again-deadline-for-disclosure-requirements-for-skilled-nursing-facilities-provider-enrollment-off-cycle-revalidations/. That is where the clean part of the timeline ends.
What followed was a stretch of repeated slippage. CMS pushed the revalidation deadline from May 1, 2025, to August 1, 2025, on April 17, 2025 https://www.foley.com/insights/publications/2025/07/skilled-nursing-facilities-cms-extends-medicare-revalidation-deadline/. Guidance meant to clarify the disclosure requirements came out May 9, 2025, though "clarify" is doing some work there, since confusion persisted well past that date https://www.foley.com/insights/publications/2025/07/skilled-nursing-facilities-cms-extends-medicare-revalidation-deadline/. On July 17, 2025, CMS moved the deadline again, this time to January 1, 2026, for submission of the new Form CMS-855A SNF Disclosures Attachment https://hallrender.com/2025/07/17/cms-extends-yet-again-deadline-for-disclosure-requirements-for-skilled-nursing-facilities-provider-enrollment-off-cycle-revalidations/. Then, on December 11, 2025, CMS dropped the fixed date entirely: no submission deadline until further notice https://www.lexology.com/library/detail.aspx?g=e669645b-620c-45d4-8030-6e7e7de832e4. Guidance updated February 24, 2026 confirmed that SNFs that had not yet submitted revalidation applications could still do so.
Four extensions inside roughly two years is not a rounding error, it is a pattern. Foley has pointed to the current administration's deregulatory posture (visible in CMS's own "Unleashing Prosperity Through Deregulation" request for information) as a plausible factor behind the indefinite delay, though that connection cannot be stated as confirmed. The delay does not mean what some might assume. CMS has instructed operators to keep collecting the required data even without a hard due date, and Crowell's client alert flagged that failure to eventually report could still cost a facility its Medicare billing privileges. So the obligation is live, even though the clock has been paused. For operators who have been treating the extensions as a green light to wait, the indefinite status is better read as breathing room to get the corporate tree mapped and the disclosure package assembled. The proposed rule was published on February 15, 2023. The final rule was published in the Federal Register on November 17, 2023 (88 FR 80141).
What the Form CMS-855A SNF Disclosures Attachment requires operators to report
Every member of the SNF's governing body must be listed, regardless of whether the facility operates as an LLC, a corporation, or a partnership. Second, every officer, director, member, partner, trustee, or managing employee, as those terms are defined in 42 CFR §424.502, has to appear on the form, with no exception for small ownership stakes.
Third, and this is where the form gets genuinely complicated, every "additional disclosable party," or ADP, has to be disclosed. An ADP is not defined by ownership percentage. Fourth, the organizational structure behind each ADP also has to be disclosed.
CMS guidance dated November 26, 2024 specifies that if an ADP is structured as a general partnership, every single partner has to be individually listed regardless of their ownership share, including in a partnership with 150 partners https://hallrender.com/2025/07/17/cms-extends-yet-again-deadline-for-disclosure-requirements-for-skilled-nursing-facilities-provider-enrollment-off-cycle-revalidations/. That is not a hypothetical edge case. A typical SNF with a management company, a separate real estate holding entity, an affiliated staffing agency, and a roster of investors is looking at a disclosure that runs long and gets granular fast, because this form was never built to function as a summary document. The underlying legal requirement is 42 CFR §424.516(g), and the practical starting point for any operator is mapping the full corporate structure before attempting to fill anything in. Every SNF must report four categories of information. Operators must report whether a party leases or subleases real property to the facility, or owns 5% or more of the total value of such real property.
The Medicare cost report's related-party rule under 42 CFR §413.17 creates a second, parallel compliance obligation
Disclosure under Section 1124(c) tells CMS who is connected to the SNF. A separate rule, 42 CFR §413.17, governs what those connected parties are allowed to charge, and it operates on a different logic entirely. The core requirement: a transaction between an SNF and a related organization has to be reported at the related organization's actual cost, not at whatever price got billed to the facility, and that cost cannot exceed what the same services would cost on the open market. Whichever number is lower, actual cost or market price, is the number Medicare will recognize.
The mechanics are easiest to see with a number. If a related management company bills the SNF $500,000 for its services but only spent $400,000 delivering them, Medicare reimburses the $400,000 https://hallrender.com/2025/07/17/cms-extends-yet-again-deadline-for-disclosure-requirements-for-skilled-nursing-facilities-provider-enrollment-off-cycle-revalidations/. The $100,000 spread does not disappear; it just becomes an unallowable cost that the facility absorbs rather than passing it through to the Medicare program. A parent organization's obvious incentive to route profit through an affiliate's markup rather than book it directly at the operating level makes this rule most visible around management companies, real estate holding entities, and staffing affiliates, all common structures in SNF ownership chains.
Section 1124(c) disclosure identifies the related parties. Section 413.17 cost reporting constrains what those related parties can actually charge. Satisfying one does not satisfy the other, and an operator can complete a flawless disclosure attachment while still misreporting related-party costs on the cost report itself.
What the OIG's December 2024 audit found and its three recommendations for SNF operators
Private equity and REIT ownership of SNFs was the specific concern that prompted CMS to activate Section 1124(c) of the Social Security Act, a provision the ACA had created but left dormant. It was structural. That is a gap wide enough to let non-compliant cost reporting sit unchallenged, year after year, simply because nobody in the review chain was checking for it.
The consequence follows directly. SNF cost reports feed straight into Part A payment calculations, and an unchecked related-party markup inflates those payments, with no federal entity consistently catching it. The audit produced three recommendations aimed at closing that gap https://oig.hhs.gov/reports/work-plan/browse-work-plan-projects/w-00-24-35887/. The first calls for MACs to fold related-party cost review into their standard desk reviews and audits going forward, a recommendation that remained open and unimplemented as of the source date, with an update expected November 12, 2025.
What does this mean practically? The recommendation still pending, folding related-party review into routine MAC audits, is the one that actually changes enforcement exposure https://oig.hhs.gov/reports/work-plan/browse-work-plan-projects/w-00-24-35887/. Once that lands, related-party cost reporting, a rule that mostly went unchecked, begins showing up in ordinary audit activity. Operators who have been treating §413.17 compliance loosely because enforcement felt thin are looking at a narrowing window. The OIG audit was conducted to check whether SNFs reported related parties as required, whether their related-party costs complied with Medicare requirements, and whether Medicare fund allocation could affect beneficiary care. The core finding was that MACs did not, as part of their normal desk reviews or audits, review the disclosure of related parties or the reporting of related-party costs, a systematic gap that allowed non-compliant cost reporting to persist. Recommendation 2 (25-A-07-028.02) called for developing and implementing guidance for SNFs on appropriate methods for determining allowable related-party costs, and it was closed as implemented July 1, 2026.
State-level disclosure obligations that stack on top of the federal framework
Federal disclosure is the floor, not the ceiling, and California illustrates that gap about as clearly as any state in the country. AB 1953 requires SNF licensees to disclose to HCAI information about ownership or control interest of 5% or more held by a related party providing services to the SNF, beginning in 2020 https://hcai.ca.gov/data/cost-transparency/long-term-care-facility-financial-data/. Once the goods or services involved cross $10,000 in value, the disclosure has to include the related party's profit and loss statement along with the SNF's Payroll-Based Journal data from the prior quarter https://hcai.ca.gov/data/cost-transparency/long-term-care-facility-financial-data/.
HCAI began collecting, reviewing, and publishing these consolidated reports starting with fiscal years ending December 31, 2023 https://hcai.ca.gov/data/cost-transparency/long-term-care-facility-financial-data/. The reports have to include basic financial statements for each operating entity, license holder, and related party sharing 5% or more common ownership that provides services to the facility, plus a statement of patient revenue broken out by payer, plus a visual diagram of the organization's structure https://hcai.ca.gov/data/cost-transparency/long-term-care-facility-financial-data/. Every SNF in the state has to submit that organizational diagram, even if it has no related parties at all. The related-party financial statement schedules themselves do not need a separate audit or CPA review, which keeps the burden somewhat lighter than it might otherwise be. HCAI then makes all of it public, which is really the entire mechanism behind the law: transparency by publication.
Colorado runs a related but narrower version tied to Medicaid participation. Any facility accepting Medicaid funds has to disclose all nursing facility ownership or affiliation with other corporations, foundations, and similar entities, including the specific type of relationship involved. Cost report schedules in Colorado go further still, requiring the name of each vendor or individual furnishing related-party supplies or services, that party's ownership percentage in the facility, a coded description of the nature of the interrelationship, and identification of any intervening person or entity along with its own ownership stake.
Operators running facilities across multiple states have to treat this as a jurisdiction-by-jurisdiction mapping exercise.
Related-party risks specific to SNFs with HUD Section 232 financing
HUD Section 232 insures mortgages for nursing homes, intermediate care facilities, board and care homes, and assisted living facilities, administered through HUD's Office of Residential Care Facilities under 24 CFR Part 232. That insurance program comes with its own reporting regime layered on top of everything already discussed. Borrowers have to submit audited annual financial statements, built to HUD's Uniform Financial Reporting Standards under 24 CFR 5.801 and 24 CFR 200.36, within 90 days of fiscal year end, filed through HUD's Financial Assessment Subsystem https://hallrender.com/2025/07/17/cms-extends-yet-again-deadline-for-disclosure-requirements-for-skilled-nursing-facilities-provider-enrollment-off-cycle-revalidations/. Quarterly reporting runs alongside that annual cycle. An updated Section 232 Handbook takes effect January 5, 2026 for all new loan applications and transactional requests tied to existing Section 232 projects https://hallrender.com/2025/07/17/cms-extends-yet-again-deadline-for-disclosure-requirements-for-skilled-nursing-facilities-provider-enrollment-off-cycle-revalidations/.
The related-party risk inside these structures has a specific shape, and it is worth understanding in detail because HUD watches for it directly. When that happens, the property company books the gap between the lease payment it is owed and the mortgage payment actually made as a lease receivable sitting on its books. Left unaddressed, that receivable can grow into a substantial balance over time. HUD reads a growing receivable as a warning sign: it suggests the operator is not actually paying the full rent required under the lease, which can amount to noncompliance with the terms of the insured loan. For any SNF operator financed through Section 232, that receivable balance is the kind of number HUD's own reviewers are trained to flag, independent of the disclosure and cost reporting obligations already in play.
Interaction of GAAP's ASC 850 and Financial Statement Audits with Regulatory Disclosure Obligations
Everything above sits inside a regulatory reporting framework, built around CMS, state health departments, and HUD. Financial statement audits answer to a separate authority entirely, and that authority has required related-party disclosure for a long time. ASC Topic 850, "Related Party Disclosures," governs how related-party relationships and transactions get disclosed under GAAP, and this has been standard accounting practice since at least July 1, 1997 https://hallrender.com/2025/07/17/cms-extends-yet-again-deadline-for-disclosure-requirements-for-skilled-nursing-facilities-provider-enrollment-off-cycle-revalidations/. That predates the CMS rule by more than a quarter century.
What that overlap means in practice is that an SNF's audited financial statements and its regulatory filings are not answering to the same standard, even when they are describing the same underlying related-party arrangements. GAAP asks whether the financial statements fairly present the transactions and relationships involved, in a way that a lender, investor, or bondholder can rely on. Section 1124(c) asks whether CMS can identify who controls the facility. Recommendation 3 concerns guidance to reeducate MACs on reviewing, granting, and documenting exception requests under 42 CFR §413.17(d). An organization can satisfy one of these frameworks cleanly and still fall short on another, since each was written to answer a different question for a different audience. CMS released a final rule requiring greater SNF ownership transparency on November 15, 2023 https://hallrender.com/2025/07/17/cms-extends-yet-again-deadline-for-disclosure-requirements-for-skilled-nursing-facilities-provider-enrollment-off-cycle-revalidations/. The CMS final rule on SNF ownership transparency was published on November 17, 2023 https://hallrender.com/2025/07/17/cms-extends-yet-again-deadline-for-disclosure-requirements-for-skilled-nursing-facilities-provider-enrollment-off-cycle-revalidations/. CMS published its proposed rule on SNF ownership transparency disclosures on February 15, 2023 https://hallrender.com/2025/07/17/cms-extends-yet-again-deadline-for-disclosure-requirements-for-skilled-nursing-facilities-provider-enrollment-off-cycle-revalidations/. The OIG audit project on SNFs' Medicare payments to related parties was completed on December 18, 2024 https://oig.hhs.gov/reports/work-plan/browse-work-plan-projects/w-00-24-35887/.
Sources
- CMS Extends (Yet Again!) Deadline for Disclosure Requirements for Skilled Nursing Facilities – Provider Enrollment Off-Cycle Revalidations | Hall Render
- Long-Term Care Facility Financial Data - HCAI
- CMS Extends Deadline Indefinitely for Disclosure Requirements for Skilled Nursing Facilities - Provider Enrollment Off-Cycle Revalidations - Lexology
- Update: CMS Extends Skilled Nursing Facilities’ Medicare Revalidation Deadline
- Skilled Nursing Facilities’ Medicare Payments to Related Parties
- Federal Register :: Request Access
- ecfr.gov
- federalregister.gov